What is a lawsuit loan? It is a phrase people commonly use for money advanced to a plaintiff while a legal case is pending, often with repayment tied to a future settlement or judgment. But the label does not tell you what the agreement requires. A plaintiff should understand whether repayment is due only from a recovery, how charges accumulate, what happens if the case produces no proceeds, and how much could be deducted when the matter resolves.
What is a lawsuit loan and what does it mean in practice?
In everyday conversation, “lawsuit loan” may refer to a funding advance offered to a person with an active legal claim. Some consumer litigation funding is structured as a non-recourse advance. In broad terms, repayment is made from a recovery if one is obtained, and the funder may bear the risk if the claim ends without a recovery. The actual agreement defines the obligation, so do not rely on a label, advertisement, or verbal description.
A conventional loan and a non-recourse advance can have different repayment arrangements. A conventional loan generally has repayment obligations set by its contract, which may continue regardless of the result of a lawsuit. An advance tied to a legal claim may instead be payable from proceeds if the agreement’s conditions are met. Read the exact terms governing a loss, dismissal, settlement, judgment, or other case outcome. If the contract is unclear about whether you would owe anything without a recovery, ask for clarification in writing and have your attorney review it.
The Milestone Foundation is a 501(c)(3) nonprofit consumer litigation funding company. It describes its products as financial advances, not conventional loans. Its funding application information explains that funding may be available before or after a settlement, depending on the case and circumstances. Neither the phrase “lawsuit loan” nor the nonprofit status replaces a careful review of the specific agreement.
What is a lawsuit loan compared with a conventional loan?
The key questions are how repayment is triggered, whether a payment schedule exists, and what happens if no money is recovered. The table below describes general distinctions, not a promise about every product. Contract language and applicable rules matter.
What triggers repayment?
Conventional loan (general example)
The agreement commonly sets payment dates or a schedule.
Non-recourse litigation advance (terms vary)
Repayment is commonly linked to proceeds from a legal claim, as the agreement defines.
What if the case yields no recovery?
Conventional loan (general example)
A debt may remain due under the loan terms.
Non-recourse litigation advance (terms vary)
A qualifying non-recourse agreement may provide that nothing is owed if there is no recovery; verify the exact language.
How can the balance change?
Conventional loan (general example)
Interest, fees, and payment terms depend on the contract.
Non-recourse litigation advance (terms vary)
Interest, fees, caps, and timing provisions depend on the funding agreement.
Who reviews the legal claim?
Conventional loan (general example)
A lender generally reviews credit and repayment factors.
Non-recourse litigation advance (terms vary)
A funder may request authorized case information, often through the attorney.
What should be compared?
Conventional loan (general example)
Payment schedule, charges, and total repayment.
Non-recourse litigation advance (terms vary)
Net amount received, projected payoff at multiple dates, fees, cap, and no-recovery terms.
Do not assume a product is non-recourse just because someone calls it an advance. Locate the section that explains repayment and look for any conditions or exceptions. Ask what the agreement means if the case is dismissed, settles for less than expected, or results in no payment to you. The Foundation’s frequently asked questions and overview of nonprofit litigation funding provide additional context about its stated approach.
Why do simple and compound interest produce different totals?
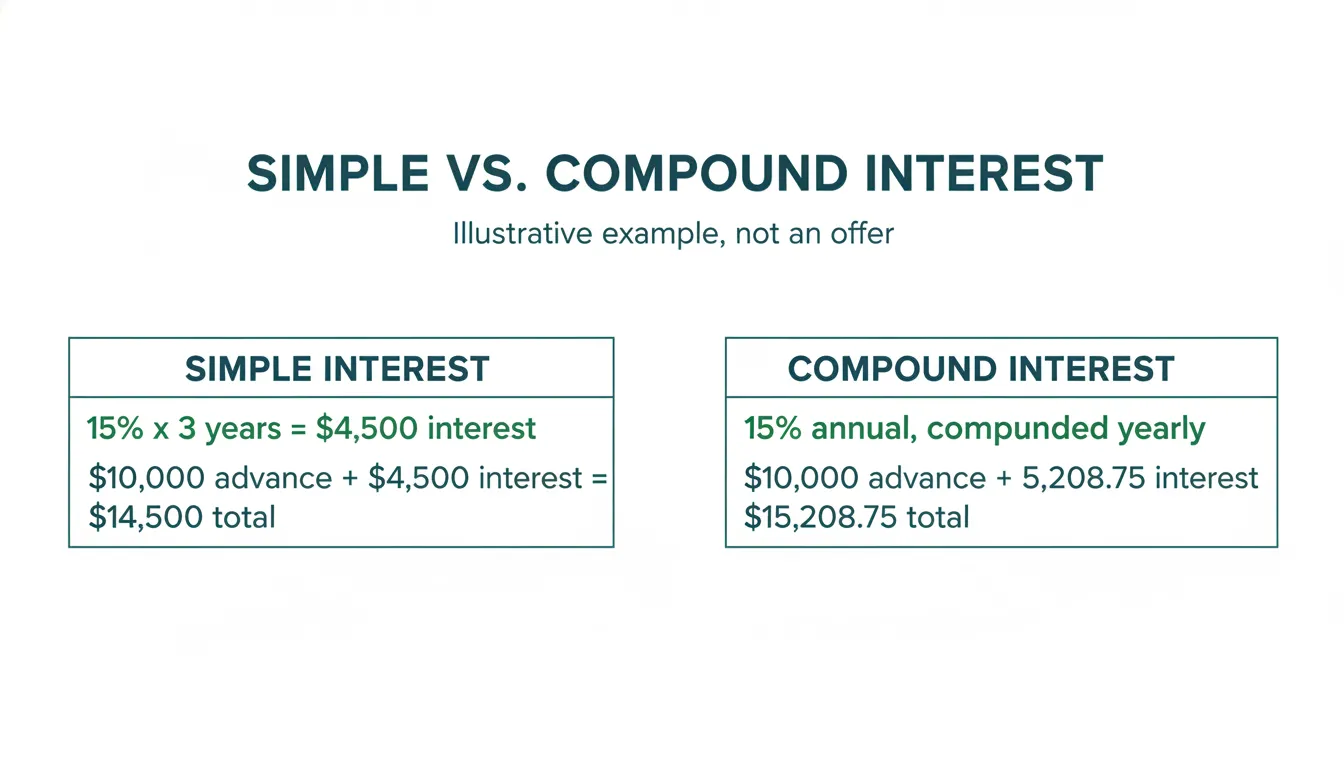
Simple interest is calculated on the original amount advanced. Compound interest is calculated on the original amount plus previously accrued interest. If an agreement compounds interest, the balance may grow faster over time because accrued interest is included in later calculations. Fees, minimum charges, and repayment caps can also affect the total. A rate alone does not show what will ultimately be payable.
For illustration only, suppose an agreement advanced $10,000 and charged 15% annual interest for three years, with no fees or payments. At simple interest, the interest would be $4,500, producing a total of $14,500. If the same nominal annual rate compounded once each year, the balance would be about $15,208.75. This example is only a way to see the difference in the arithmetic. It is not a quote, prediction, or representation of any offer. Actual terms may calculate charges differently, and the agreement controls.
When you review an offer, ask in plain language:
- Is interest simple or compound, and when does accrual begin?
- How often is interest calculated or added to the balance?
- Are there fees at the start, during the case, or at repayment?
- Does a cap limit the total payoff, and how is that cap applied?
- Can additional advances or amendments change the balance?
Request payoff estimates in dollars at several possible resolution dates. The figures should specify the amount you would receive, charges, and assumptions used for each estimate. A balance at six months may look very different from one at two years. Make sure you compare estimates prepared on the same timeline and with the same amount advanced.
The Office of the Comptroller of the Currency publishes interest rate risk statistics reports based on examinations of banks it supervises. Those reports concern banks, not consumer lawsuit advances, and do not establish the terms of any funding agreement. They are a reminder that interest-rate exposure is analyzed in financial contexts; for an individual plaintiff, the relevant figures are the calculation method and payoff estimates in the written contract.
What should you check before accepting an offer?
Use the agreement and written payoff estimates as your source of truth. Before signing, separate what you receive now from what may be repaid later. A concise checklist can keep important terms from getting lost in a long document:
- Confirm the net amount. Identify the amount delivered to you and whether any fee is deducted before payment.
- Find the repayment trigger. Confirm whether payment is tied to a recovery, what counts as a recovery, and how the funder is paid.
- Understand no-recovery language. Read the part addressing a lost, dismissed, or otherwise unsuccessful case. Check whether any exceptions or conditions apply.
- Trace every charge. Note the rate, simple or compound method, accrual frequency, and any fees or minimums.
- Ask for multiple payoff figures. Request estimates for reasonable timeframes and the assumptions behind them.
- Check for a cap and changes. Understand any repayment limit and how future advances, amendments, or case events affect it.
- Review timing and cancellation terms. Ask whether early payoff is allowed and how it would be calculated.
- Take time for attorney review. Ask counsel how the agreement could affect case proceeds and whether the information-sharing process raises concerns.
Compare offers using the same assumed advance and resolution dates. Put the net cash, payoff at each date, fees, cap, and no-recovery terms next to one another. Do not compare one provider’s annual rate with another provider’s total dollar payoff as if they were the same measure. If a provider will not explain its calculation or provide clear written terms, pause before agreeing.
It can also help to write down the specific expense the advance is meant to address and when it is due. Then compare that need with the amount you would receive and the possible reduction in proceeds later. This is not a forecast of the case result. It is a way to make the tradeoff concrete and consider whether other options or waiting might be preferable.
Why does the attorney participate?
A funder may need information about the claim, its status, and the expected path to resolution to evaluate a request. With the plaintiff’s authorization, the attorney may answer questions or provide case information. The precise process varies. Before authorizing disclosures, ask what information is requested, who will receive it, and how it will be used.
The attorney’s involvement does not make the attorney the borrower or transfer control of the lawsuit to the funder. The plaintiff and counsel remain responsible for decisions about the case, including whether to accept a settlement. Do not assume the funder has authority over legal strategy. Ask your attorney to explain any contract term that could affect the case or the distribution of proceeds. The Foundation’s information for attorneys describes its attorney-facing resources, while its overview of advance requirements discusses information that may be relevant to an application.
Attorneys can help identify case-specific concerns and explain how repayment might fit into the resolution process. They cannot make the funding decision for the plaintiff. Give counsel enough time to review the complete agreement, not only a summary or a proposed payoff number.
How does The Milestone Foundation describe its funding?
The Milestone Foundation is a 501(c)(3) nonprofit organization and consumer litigation funding company. It describes its model as mission-focused and offers pre-settlement and post-settlement advances. The Foundation states that its advances use simple interest and that total repayment is subject to a 2X cap; the written agreement for a particular transaction sets the applicable terms. Ask for a dollar payoff illustration and confirm exactly how any cap applies before making a decision.
A nonprofit structure does not remove the need to read a contract, compare costs, or consider whether an advance suits your circumstances. It also does not guarantee that a particular request will be approved or that a case will resolve in a certain way. Review the Foundation’s background and nonprofit mission alongside the terms offered for your case. The fair pre-settlement funding guide offers further information about the organization’s approach.
How can you compare total repayment step by step?
Use one worksheet for each offer. The goal is not to predict the settlement or decide whether an advance is right for someone else. The goal is to understand the possible dollars and conditions on the same basis.
- Write down the amount you would actually receive after any deductions.
- Record every charge and how it is calculated.
- Mark whether interest is simple or compound and its accrual schedule.
- Ask for written payoff totals at several time points, such as six months, one year, and two years, when appropriate.
- Note the cap, early-payoff terms, and any conditions that could change the figures.
- Read the no-recovery provision and record what the agreement says happens if there are no proceeds.
- Review the worksheet and agreement with your attorney before signing.
For example, if two offers provide the same net amount, put each provider’s estimated payoff at one year and two years in adjacent columns. Add a separate note for how a case loss is treated. That comparison may show that a lower initial charge is not the only relevant difference, or that the same-looking rate produces different outcomes because of compounding, fees, or a cap. If the estimates use different assumptions, ask each provider to recalculate them on matching assumptions rather than guessing.
If you would like to ask the Foundation how its application and review process works, you can use its plaintiff funding information. A request for information is not a commitment to sign; take time to review the terms and consult your attorney.
Contact the Foundation with a question
What should plaintiffs remember about lawsuit funding?
What happens if my case loses?
Check the written agreement rather than relying on the phrase “non-recourse.” Find the clause about no recovery and confirm whether it addresses dismissal, an unsuccessful outcome, or other circumstances. Ask the funder to explain any exception, and ask your attorney to review it. The protection depends on the contract’s actual wording.
Will an advance reduce what I keep from a settlement?
If repayment is due under the agreement, it is generally paid from proceeds, which can reduce the amount left for you. To understand the possible effect, compare a range of hypothetical recovery amounts with the projected payoff and any other obligations that may apply. These examples cannot predict the result of a case. Your attorney can help explain case-specific issues.
Is a lawsuit advance right for every plaintiff?
No. Consider the immediate need, the amount you would receive, the possible payoff over time, and other options that may be available. If there is no urgent need, waiting or exploring alternatives may be worth discussing with counsel. If you consider an advance, review the complete agreement, request estimates in writing, and make your own decision after understanding the tradeoffs.
What is the bottom line?
“Lawsuit loan” is a broad everyday phrase, not a complete description of a financial product. Focus on the written terms: whether repayment depends on a recovery, what happens if there is no recovery, how interest and fees accumulate, and what the payoff could be at different points in time. Compare offers on the same assumptions, involve your attorney, and make sure you understand the agreement before signing.