Arkansas Litigation Funding Regulations: Plaintiff Guide
If you are researching Arkansas litigation funding regulations before accepting a pre-settlement advance, start with the written agreement and an attorney review. Compare the total repayment, not only the advertised advance or a monthly rate. Arkansas plaintiffs should understand the state’s consumer lawsuit lending rules, the required APR disclosure, and the difference between simple and compound charges.
Call (716) 970-7100 to discuss funding options or review funding resources for attorneys.
What Arkansas litigation funding regulations address
Arkansas regulates this area through its consumer lawsuit lending statute, Arkansas Code section 4-57-109. The Legislature’s official record for Senate Bill 882 says the 2015 measure, titled “To Regulate Consumer Lawsuit Lending,” became Act 915. A later technical-corrections bill, House Bill 1318, became Act 261 in 2017. The 2025 compilation of the statute still carries both session-law citations.
The statute defines a consumer as a person who is, or may become, a plaintiff or claimant in a dispute. A dispute can be a civil action, an alternative dispute resolution proceeding, or an administrative proceeding before a state agency. Consumer lawsuit lending covers two ideas. One is providing money for a purpose other than prosecuting the dispute, when repayment comes from the consumer’s proceeds. The other is buying a contingent right to a share of those proceeds.
Those definitions matter in a client conversation. An advance used for rent, food, or transportation can still fall inside the statute if repayment is tied to the case. A purchase of a share of future proceeds can fall inside it too. The label on a marketing page does not control the analysis. The contract and the current statute do.
What the statute says about interest and disclosures
Section 4-57-109 points to the maximum interest rate in section 4-57-104. That section says the parties may agree in writing to interest that does not exceed the applicable rate in Arkansas Constitution Amendment 89. Amendment 89, section 3, states a maximum of 17 percent per year for loans or contracts that sections 1 and 2 of the amendment do not describe. Any amount paid to the funder above the money provided to the consumer counts as interest for that maximum-rate test.
The agreement must be in writing. It must prominently disclose the annual percentage rate. The statute specifies bold, 20-point Arial type inside a black rectangle with a 1.5-point border. A violation is a deceptive and unconscionable trade practice under section 4-88-107, with the remedies in the Deceptive Trade Practices Act.
This overview is not a legal opinion. Later amendments, court decisions, and the facts of a particular deal can change the answer. Ask an Arkansas attorney to read the current code and the agreement before anyone signs.
Why current-law verification matters
An archived bill page is useful history. It is not a substitute for the code your client would rely on today. Counsel should check the current section, later acts, and any decision that interprets consumer lawsuit lending. The purpose of the money, the parties, and the repayment formula can all change the analysis.
Ask counsel three narrow questions. Do the definitions in the contract match the current statute? Is the stated APR complete, including amounts the statute treats as interest? Does any clause confuse control of the case or who must repay if there is no recovery?
Keep the agreement, the repayment illustration, and the written answers. If a provider will not explain a term in writing, pause. Do not treat a verbal assurance as a disclosure the statute would recognize.
How to review an Arkansas funding agreement
Pre-settlement funding is generally a non-recourse advance tied to a pending civil claim. The plaintiff receives money before the case ends. Repayment is normally taken from a recovery the contract describes. It is not a bank loan, and it is not legal advice. The attorney still owns case strategy, timing, and settlement decisions.
For a separate explanation of total cost, use the pre-settlement funding cost guide. Use it to frame questions. Then rely on the Arkansas contract and current advice, not on a national example.
Arkansas funding agreement review checklist
| Review area | Question to ask | What to confirm |
|---|---|---|
| Definition and purpose | How does the contract describe the deal? | Plain description of the advance and the repayment right |
| Advance and deductions | What amount will the client actually receive? | Gross amount, each deduction, and net funds |
| APR and charges | How is the rate calculated? | Prominent APR, starting balance, and formula |
| Amounts above the advance | What else is owed beyond the money received? | Whether those amounts count as interest under section 4-57-109 |
| Other fees | Are charges added outside the stated rate? | Fee name, amount, timing, and who pays |
| Repayment | What could be owed at different durations? | Written dollar examples and any cap |
| No recovery | What happens if the claim produces nothing? | Non-recourse conditions and any duties that remain |
| Attorney review | What must counsel confirm? | Review, settlement instructions, and distribution |
The guide to rates, eligibility, and attorney review adds questions that apply beyond Arkansas. The goal here is narrower. Understand the dollars, the APR box, and the risks before future settlement money is committed.
How to read the APR box
A percentage helps only when you know the balance and the schedule. Ask whether the figure is an annual percentage rate, a monthly rate, a fixed fee, or an estimate for one payoff date. Ask for the amount due at several durations. Separate the approved amount from the net amount the client receives.
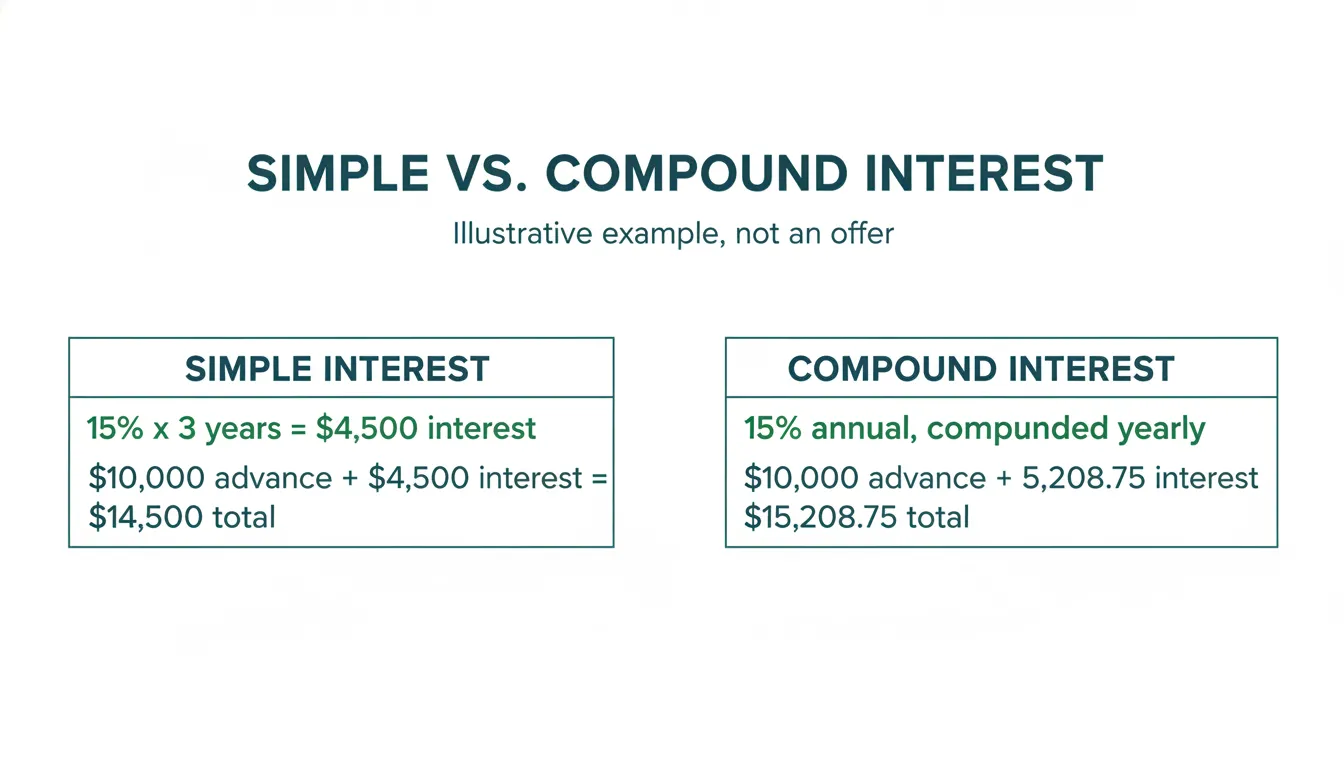
Simple interest is calculated on the original advance. Compounding applies a charge to a growing balance, so the cost can rise faster as a case continues. Ask for the starting balance, the rate, the accrual period, and any separate fee in writing. If the contract uses a cap, ask whether the cap includes principal, interest, fees, or only some of those amounts.
The statute also tells you where to look. The APR must be prominent, in the specified bold type and border, not buried in a footnote. If you cannot find that box, treat the disclosure as incomplete until counsel says otherwise.
For background on simple versus compound charges, read the simple-interest lawsuit funding cost guide. Then have counsel apply those questions to the Arkansas agreement. Do not treat a general example as the rate in this contract.
What attorney review should cover
Attorney review is more than a signature. Counsel can see how the funding contract interacts with the retainer, medical bills, liens, costs, and the expected distribution. Ask what changes if the case ends early, runs long, produces a smaller recovery, or produces none.
- Confirm the net amount the client will receive, and whether a smaller advance would meet the need.
- Check projected repayment at several realistic time points.
- Identify fees, the rate formula, any cap, and the conditions of non-recourse treatment.
- Review who receives settlement proceeds and how the funder is paid.
- Confirm the contract does not interfere with counsel’s duties or the client’s authority over settlement.
Attorneys who want a broader disclosure framework can use the guide to disclosing litigation funding rates. Process questions can also go through attorney funding resources.
How a nonprofit company can fit the comparison
A nonprofit structure does not make an offer suitable by itself. It does not replace the statute or the contract. It can change the purpose of the capital. The Milestone Foundation is a 501(c)(3) nonprofit company. Its current site says it is a nonprofit consumer litigation funding organization. It describes pre-settlement advances at 15 percent simple annual interest, with no compounding, and a repayment cap of two times the amount advanced. Post-settlement funding is described at 10 percent simple interest. Funding is non-recourse: if the case does not recover, the plaintiff owes nothing under that model. Confirm the offer you actually receive.
Those figures come from the organization’s current public funding information, checked in November 2026. They are not a statement of Arkansas’s maximum rate, and they are not a quote for every case. Eligibility still depends on an active lawsuit and a licensed attorney. Terms vary by case.
Size the request to a real need. A smaller advance can mean less to repay later. Housing, utilities, food, transportation, and medical costs are the usual reasons to ask. The requirements for a lawsuit advance explain information a funder may request. That page is about the file, not about Arkansas law.
Call (716) 970-7100 to review a funding question or learn about applying for nonprofit funding. Speak with your attorney before signing.
A short client conversation
Use a fixed order so the statute, the dollars, and the decision stay separate. The order below is a conversation aid. It is not a compliance checklist and it is not legal advice.
- Name the statute. Tell the client that Arkansas Code section 4-57-109 addresses consumer lawsuit lending, and that counsel must confirm it still reads the same way.
- Show the writing requirement and the APR box. If the box is missing, stop and ask for a complete contract.
- Separate the net advance from every amount above it. Remind the client that amounts above the advance can count as interest for the maximum-rate rule.
- Walk through no-recovery language, liens, and who gets paid at settlement.
- Compare only after the Arkansas contract is clear. A nonprofit 15 percent simple-interest option can be one comparison, not a substitute for the review.
End by writing down what the client decided and what counsel still needs to verify. A rushed signature is the failure mode this statute’s disclosure rule is built to slow down.
What this brief does not decide
This page does not say whether a particular Arkansas offer is legal. It does not calculate the client’s repayment, and it does not pick a funder. Those answers depend on the current statute, the contract, and the case. A national cost article answers a different question: what pre-settlement funding tends to cost. Send readers there when they ask for rate math. Keep them here when they ask what Arkansas requires in the agreement.
Counsel should also separate consumer lawsuit lending from funding the law firm’s own expenses. Section 4-57-109 is aimed at a consumer’s proceeds. A different arrangement may follow different rules. If the papers are unclear about who receives the money and who must repay it, that is a reason to stop and rewrite the explanation before anyone signs.
Plaintiffs can use the same boundary. If an ad promises the lowest cost but will not show the APR box, the net deposit, and a no-recovery clause, the ad is not the disclosure. Ask for the contract. Then ask an Arkansas lawyer to read it. The phone number and attorney page above are for a funding conversation, not a substitute for that review.
Frequently asked questions
What are Arkansas litigation funding regulations?
Arkansas Code section 4-57-109 addresses consumer lawsuit lending. It came from Act 915 of 2015, with a 2017 technical correction in Act 261. The statute covers certain advances and purchases of case proceeds, applies a maximum-interest rule, requires a written agreement with a prominent APR, and treats violations as deceptive trade practices. Ask an Arkansas attorney to confirm the current text.
What should an Arkansas funding agreement disclose?
Review the advance, deductions, fees, APR, projected repayment, and any cap or non-recourse condition. The statute calls for the APR in bold 20-point Arial type inside a bordered box. Ask counsel how the agreement affects settlement distribution.
Is The Milestone Foundation a nonprofit company?
Yes. The Milestone Foundation is a 501(c)(3) nonprofit company. Its public funding information describes pre-settlement advances at 15 percent simple annual interest, no compounding, and non-recourse terms. Confirm current eligibility and the contract you are offered.
What if the Arkansas case does not recover?
Read the contract’s no-recovery language, including conditions and any duties that continue. Under The Milestone Foundation’s published non-recourse model, the plaintiff owes nothing if the case does not recover. Another provider’s contract may differ. Ask Arkansas counsel to explain the clause in front of you.
Bottom line
Arkansas litigation funding regulations are one part of a careful review. Verify section 4-57-109, read the APR box, and have counsel check amounts the statute treats as interest. Compare projected dollars, not marketing labels. A clear nonprofit option may be worth a look, but only after the written agreement is understood.